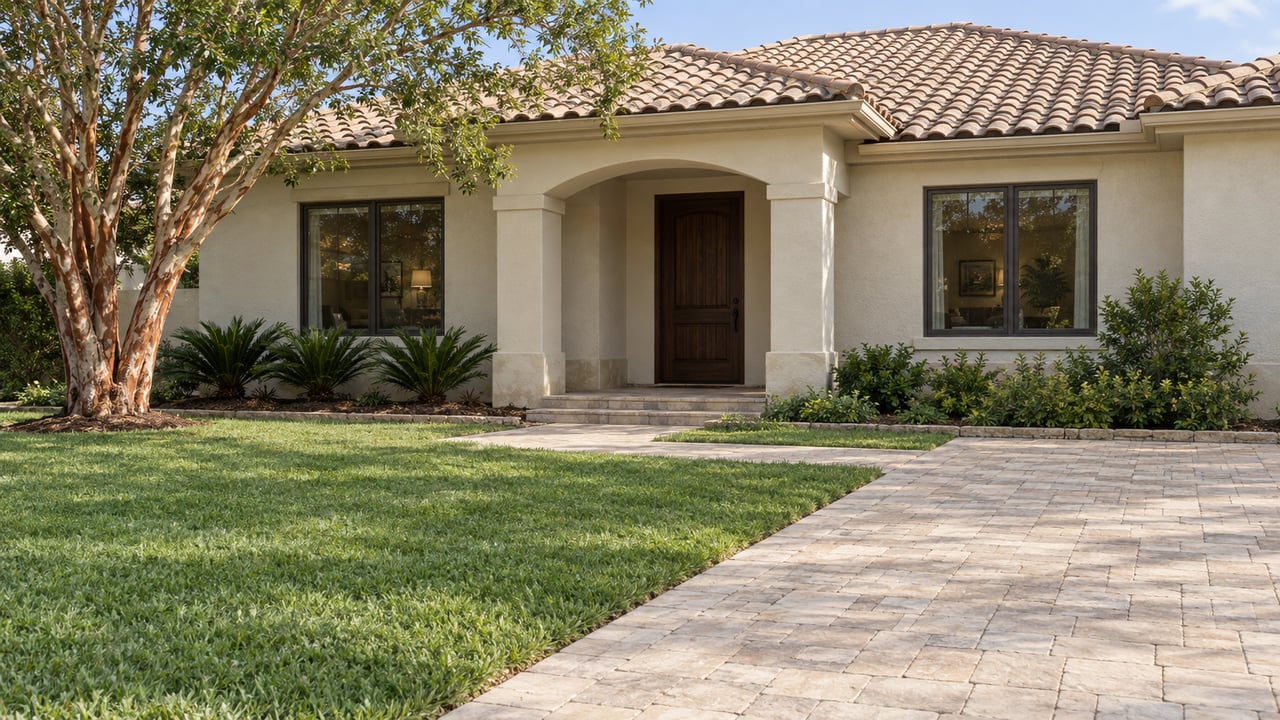
The house at 15785 Genova Drive in Esplanade by the Islands is a Taylor Morrison Lazio II on Lot 604. It has a water view and is expected to be ready between December and January 2027. On the builder's site in late October, its price was $936,151. The $1,036,151 price above it had a line through it, and next to that was "Save $100,000."
That $100,000 cut is the part buyers can see. The builder was also offering a lower mortgage rate, credits toward closing costs and up to a year of HOA dues, and "flex cash" that could go to options or a lot premium. Some of those discounts lower the price written on the contract. Others reach the buyer through the loan and the closing statement. For anyone comparing a new East Naples home with a resale a few streets away, that split decides what the competition really costs.
The best discounts depend on the builder's lender and the seller's closing agent
Before the numbers, look at a condition in Taylor Morrison's own fine print. To get the financing promotions, a buyer had to pre-apply with Taylor Morrison Home Funding before making an offer, finance through that lender, and close with the closing agent the seller picks. The builder's terms say buyers are free to use a different lender or title company. Those buyers simply don't get the financing incentive.
Here is what was offered in the Fort Myers/Naples division on Taylor Morrison's current promotions page for contracts dated October 19 through November 1, 2026:
| Incentive | Terms | Lender requirement | How it is recorded |
|---|---|---|---|
| Price reduction on select quick move-in homes | Up to $100,000 off, for contracts closing on or before Nov. 30, 2026; excludes Esplanade Kingston | None; cash buyers qualify | Already taken off the price on the purchase agreement |
| $60K flex cash | Toward options or lot premium; quick move-in homes must close by Dec. 31, 2026 | None for options or lot premium | Shown as a price reduction on the purchase agreement |
| Same flex cash used for financing | Temporary buydowns, points, closing costs, up to one year of HOA dues | Affiliated lender required | Paid at closing as a seller contribution |
| 30-year fixed | 5.49% rate, 5.60% APR, plus up to $6,000 toward buydown, closing costs, HOA dues or prepaids | Affiliated lender required | Paid at closing as a seller contribution |
| 7/6 ARM | 4.25% initial rate for 84 months, then adjusts every six months, with a 9.25% lifetime cap; 5.49% APR on the builder's sample loan; up to $4,000 toward costs | Affiliated lender required | Paid at closing as a seller contribution |
The table shows two separate kinds of discount. A price reduction, or flex cash used for options and the lot premium, lowers the contract price. Flex cash used for a rate buydown or closing costs leaves the contract price where it is and shows up as a seller contribution at closing. Both cost the builder money, but only the first lowers the sale price that gets recorded.
The contract window for this round closed November 1. The price-reduction terms ran through closings on or before November 30, and Taylor Morrison reserves the right to change pricing and incentives at any time before a contract is signed. By the time you read this, the offer may have changed. The way the incentives are built probably hasn't.
The fine print under the East Naples median
The Naples Area Board of Realtors' September 2026 market report is the most recent release. It came out October 23 with data current as of October 10. The East Naples page has a footnote under the price figures:
"Does not account for sale concessions and/or downpayment assistance."
That means a $40,000 closing-cost credit or a builder-paid buydown doesn't lower the closed price NABOR reports. A straight price cut does. The median combines both kinds of sales, and it can't tell which incentive a builder used.
With that in mind, here are the East Naples single-family figures for September 2026:
- Median closed price: $608,495, down 4.5% from $637,450 in September 2025
- Year-to-date median through September: $630,000, down 2.3%
- Year-to-date average closed price: $813,734, up 3.2%
- Year-to-date sales: 1,336, up 12.3% from 1,190
- Inventory: 766 homes, down 13.4%, or 5.4 months of supply compared with 7.2
- Share of list price received: 96.9%, up from 95.4%
Countywide, excluding Marco Island, the single-family median rose 3.1% to $747,500 over the same September comparison.
So in East Naples, more homes are selling, fewer are listed, and sellers are getting closer to their asking price, yet the median has slipped. The data doesn't explain why. Some of the drop could be a different mix of homes selling, and the average rising while the median falls points that way. Either way, the true discount in East Naples is at least what the median shows. Any builder deal paid through the loan rather than the price would only make the net price lower than the published figure.
Two details matter when you use these numbers. First, NABOR's "East Naples" covers ZIP codes 34114, 34117, 34120 and 34137, so it reaches well past the US-41 East corridor. Second, ZIPs 34112 and 34113 count as South Naples in NABOR's reports. ZIP 34114 alone, where Esplanade by the Islands is, had a September 2026 median of $575,000, up 3.1%, with 61 sales, 413 homes in inventory and 100 days on market.
Why a builder would rather pay through the loan
Taylor Morrison isn't alone. In NABOR's September commentary, Mike Bone, director of sales at Christopher Alan Homes, said, "Builders are offering $30,000 to $50,000 in concessions, or paying closing costs, or buying rates down to as low as 5 percent." He added that builders are cutting starts, "which are down roughly 50 percent in the area." In August, the Naples Daily News reported that Southwest Florida builders were offering deals to unload vacant new homes and that local buyers were showing less interest.
Nationally, the Appraisal Institute cited National Association of Home Builders figures from August 2026. That month, 63% of builders used sales incentives, while 35% cut prices, by an average of 6%. The Institute describes incentives and price cuts as "competing tools."
The choice between those tools matters at appraisal. The same Appraisal Institute piece cites Fannie Mae data from 2023, which found that appraisers made no adjustment in 58% of comparable sales that involved concessions. When appraisers did adjust, 86% subtracted the full dollar amount. Fannie Mae has since warned against assuming either no impact or a full dollar-for-dollar impact, and it accepts a full adjustment only when market analysis supports one. Its Selling Guide section B4-1.3-09 treats rate buydowns as financing concessions and calls for adjustments based on how the market actually responds to them.
The Institute also walks through a hypothetical new-construction sale. In it, the builder, lender and title company are affiliated, and buyers who use them get incentives that buyers financing elsewhere don't. When the lender reports only the total concessions, the appraiser has to judge the whole package, and as the market softens, the adjustments "may reduce support for the builder's contract price." That hypothetical describes a general structure, not any particular local builder. It does show why it matters whether an incentive lowers the contract price or is paid at closing.
Where the builder has left
Not every East Naples community still has a builder selling. Minto announced on March 3, 2026 that it had sold the last new home at The Isles of Collier Preserve. Every home for sale there now is a resale. A seller in that community is competing with other owners, none of whom can offer a 4.25% starting rate or a year of HOA dues.
At Esplanade by the Islands, a resale owner competes with the builder's spec homes on the next street. Taylor Morrison lists base prices from $599,999 to $1,110,999 there. Its coach homes in the quick move-in inventory were listed at $629,476 and $632,236, each $40,000 below the earlier price. For a resale buyer, the useful comparison is the builder's price after its incentive, not the price that gets recorded.
Five questions to ask before you compare two East Naples prices
- Which discounts are already in the contract price, and which are paid at closing? Taylor Morrison's terms say quick move-in price reductions and flex cash used for options are written into the purchase agreement. Finance incentives are paid at closing.
- What does the offer cost if I use my own lender? Comparing quotes with and without the affiliated lender shows how much of the deal depends on financing.
- When does a 7/6 ARM's low rate end? The advertised 4.25% lasts 84 months. After that, it adjusts every six months and can reach 9.25%.
- Is the home in 34114, or somewhere else in NABOR's East Naples area? The ZIP-level figures and the wider East Naples figures moved in opposite directions in September 2026.
- Is a builder still selling in this community? That decides whether a resale is competing with incentives or only with other owners.
The rate, lender and appraisal rules above come from published builder terms and industry guidance. This is general information, not legal, tax or financial advice, so confirm how they apply to your purchase with your own lender, attorney or tax professional.
Frequently asked questions
Are the late-October Taylor Morrison financing offers still available? The contract window for the 5.49% fixed rate, the 4.25% ARM and the $60K flex cash ran from October 19 through November 1, 2026. The quick move-in price reductions apply to contracts closing on or before November 30, and the builder can change its offers at any time before a contract is signed.
Do 34112 and 34113 count as East Naples in NABOR's statistics? No. NABOR puts those ZIP codes in South Naples. Its East Naples figures cover 34114, 34117, 34120 and 34137.
Do I have to use the builder's lender to buy a new home? Taylor Morrison's terms say you don't. You do need its affiliated lender and the seller's closing agent to get the financing promotions.
If you're weighing a builder's spec home against a resale in East Naples, Brian Giacomello can help you compare the two side by side, from the contract price and the credits paid at closing to the comparable sales an appraiser is likely to use. Start Your Success Story with a real comparison of what each home costs you.